WInsights
  • UHNW Event Calendar 2026

  • Contact

  1. Home
  2. WInsights
  3. article

A Different Way to Manage Wealth for Indian HNIs

Kartik Kini

|

17 July 2025

HNI

Wealth Management

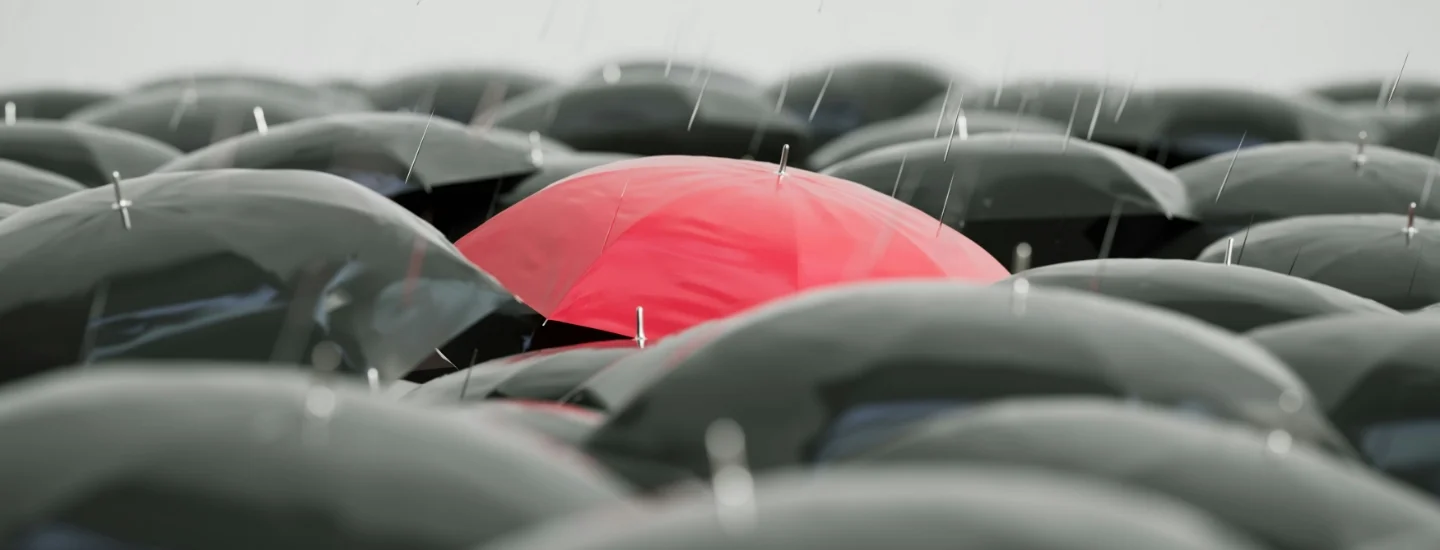
A red umbrella among grey ones, like a different model of wealth management for Indian HNIs.

India is at an inflection point in its wealth journey. In 2024, the number of ultra-high-net-worth individuals (UHNIs)—those with assets above $30 million—grew 6% annually to 13,600, a number projected to increase by 50% by 2028. At the same time, the high-net-worth individual (HNI) population—those with assets above $1 million—has crossed 850,000 and is set to nearly double to 1.65 million by 2027.

This growth reflects a dramatic shift in HNI wealth trends in India, with 20% of millionaires now under 40, representing a younger, digital-first generation. Wealth creation is no longer limited to metros; Tier-II and Tier-III cities like Jaipur, Pune, and Indore are emerging as wealth hubs, powered by digital access and entrepreneurial growth.

Behind this surge are structural tailwinds such as the booming startup ecosystem, formalisation of the economy, and financialization of household savings. Flagship programs by the Indian government, like ‘Digital India’ and ‘Make in India’, as well as its PLI schemes have created fertile ground for sectors like tech, manufacturing, and financial services and are key drivers of the next-gen wealth India is experiencing.

Evolving Wealth Management Expectations

HNIs in India have built their wealth through a variety of means. Many are first-generation entrepreneurs who are risk-takers with an aggressive mindset toward capital growth. Others belong to legacy business families, often grappling with a more layered challenge: preserving and growing inherited wealth while staying relevant in a rapidly changing world.

A growing number are professionals, CXOs, and startup founders whose liquidity events have catapulted them into wealth categories once seen as reserved for industrialists. This proliferation of HNIs is amplified by a once-in-a-lifetime event: the Great Wealth Transfer. Globally, an estimated $84 trillion is expected to be passed down from baby boomer parents to their millennial and Gen Z children by 2045, signalling the emergence of next-gen inheritors.

Concurrently, the asset landscape is becoming more sophisticated. Private equity, venture capital, AIFs, REITs, global portfolios, and collectables are making asset allocation more nuanced. Add in tax regulations, ESG frameworks, and cross-border considerations, and it’s clear that modern wealth management in India requires far more than just product selection—it demands strategy, alignment, and deep understanding.

Against this backdrop, the models of engagement in wealth management are evolving. India’s wealth management industry, which stood at $1.1 trillion in AUM in FY24, is expected to more than double to $2.3 trillion by FY29.

The 3 wealth management models in India

The growth in the number of HNIs in India is paving the way for differentiated wealth management models. Each has its own appeal, depending on the investor’s needs, risk appetite, and stage in the wealth journey.

  • Distribution-led models

The distributors-driven model and relationship managers at banks and large institutions represent the most traditional wealth management approach that operates on a commission-based structure. They focus on selling products that are suitable but not always optimal, raising concerns around bias and conflict of interest. While distribution models still command a significant share of the wallet, especially among older clients, trust is increasingly shifting toward those perceived as more aligned with investor outcomes.

  • Fee-based advisory models

Pure advisory players offer unbiased, product-agnostic guidance in exchange for a flat fee. These could be boutique firms, specialised advisory firms or independent wealth advisors who prioritise transparent advice over product selling. This segment is growing rapidly as clients become more aware and seek alignment over incentives.

  • Tech-only platforms

Platforms like Zerodha, Kuvera, Groww, and INDmoney are designed for the digitally native, cost-sensitive investor. They offer low-cost access, transparency, and convenience, with features like direct mutual fund investments, goal tracking, and tax optimisation. But for all their simplicity, they often lack the nuance and strategic foresight required for complex, multi-generational wealth management.

In India, the Securities and Exchange Board of India (SEBI) — particularly its Investment Advisors Regulations of 2013 — has been instrumental to the transformation of the country’s wealth management landscape. The regulations aimed to protect investors by providing a framework that regulates anyone offering investment advice and ensures that their advisory services are transparent, unbiased, and conflict-free. The framework brought structure and accountability to the advisory process and has served as an impetus that propelled the adoption of the advisory model in India.

Over the years, India’s HNIs have shown a growing preference for a fee-based wealth-advisory model over traditional approaches to wealth management. This shift signals the demand for not just sophisticated services aligned with global best practices but also a framework that instils trust and prioritises the client’s best interests.

From accumulation to alignment

As India’s wealth landscape evolves, there is a growing demand for more specialised advisory services that offer bespoke solutions for specific needs, risk appetites, and stages in the wealth journey. Distinct client segments have also emerged, where wealth management advice is tailored to the unique circumstances of each cohort, from entrepreneurs, first-gen HNIs, and next-gen inheritors to NRIs, women, and family businesses.

This evolution in India mirrors a broader global trend. In mature markets like the US, UK, and Australia, the dominance of product-push models has steadily given way to advisory-led engagement. A recent PwC survey points out that HNIs increasingly prioritise services beyond traditional investing, reinforcing this evolution. The most in-demand: tax and legal advice (31%)—especially succession planning—followed by real estate (23.1%) and M&A advisory (19.4%).

This shift marks a transition where advisory services prioritise meaningful, goal-based partnerships over transactional selling.

The future leads towards advisory-first

As it stands, customised advice encompassing various facets of financial wellbeing is now the bedrock of every high-net- worth client’s expectations from their wealth advisor. The success of wealth management will be determined by how well a wealth manager can build lasting trust through transparent, unbiased advice that prioritises client goals over product sales. Advisors who focus on understanding clients’ unique circumstances and delivering personalised, un-biased, goal-aligned strategies will outperform traditional, transaction-driven models.
Advisory For Media Sports Entertainment Professionals

Advisory For Media Sports Entertainment Professionals

Frequently Asked Questions

What are the different types of wealth management models in India?

Broadly three: distribution-led (bank RMs selling products on commission), fee-based advisory (flat, transparent fees, no product bias), and tech-only platforms (low-cost, self-directed apps). Which one suits you depends on how complex your portfolio is and how much personal guidance you need.

What is a distribution-led wealth management model?

It's the traditional setup you see at most banks, a relationship manager recommends products and earns a commission on what you buy. It works fine for simple needs, but since the RM's income depends on what's sold, the "best fit" product for you isn't always what gets recommended.

Why are HNIs in India shifting toward fee-based wealth advisors?

Two big reasons: they want advice that isn't influenced by commissions, and SEBI's 2013 regulations made fee-based advisory more transparent and accountable. As portfolios get more complex (AIFs, PE, global assets), people simply want someone whose only job is looking out for them.

Who qualifies as an Ultra High Net Worth Individual (UHNWI), and how fast is this segment growing?

A UHNWI typically has assets above USD 30 million. India has around 13,600 of them today, growing about 6% a year and that number could grow by 50% more by 2028.

What role does SEBI's Investment Advisors Regulations, 2013 play in wealth management?

It's the rulebook that requires investment advisors to give transparent, unbiased advice . It's a big reason fee-based advisory has grown it gave clients a real reason to trust the process.
MORE INSIGHTS

Top-down view of a winding spiral staircase

HNI

UHNI

Wealth Management

What Is Open-Architecture Wealth Management?

Learn how open-architecture wealth management works, how it differs from traditional wealth management, and what investors should know.

Article •12 November 2026
Ornate wooden desk and leather chairs in a traditional private office.

Entrepreneurs

UHNI

Family Office

Wealth Management

Why Family Offices Are Growing in India

Explore how rising wealth and increasingly complex investment needs is giving rise to a holistic way to manage wealth.

Article •10 November 2026
Soumya Rajan on a Mint Money thumbnail with the headline “How Rich People Invest Their Money

Global Investment

HNI

UHNI

Wealth Management

Alternative Investments

How Do Rich People Invest? In Conversation with Soumya Rajan

Soumya Rajan on a Mint Money thumbnail with the headline “How Rich People Invest Their Money

Podcast •08 August 2026
Airplane flying through a circular opening in a modern architectural structure.

Global Investment

HNI

UHNI

Wealth Management

What Is GIFT City? How Families Can Use It for Global Investing

Explore how Indian families can invest globally through GIFT City, including LRS, Family Investment Fund, tax considerations, benefits and risks.

Article •17 November 2026
Business professional in a suit holding a smartphone.

HNI

UHNI

Wealth Management

Bank-Owned vs Independent Wealth Management Firms in India

Compare bank-owned and independent wealth management firms in India, including fees, regulation, conflicts of interest and how to choose an advisor.

Article •16 November 2026
Stack of gold coins with a rupee symbol surrounded by grass and flowers. Related Article: ESG and Impact Investing

HNI

UHNI

Family Office

Impact Investing

What Is Impact Investing? A Guide for India’s HNIs & UHNIs

Understanding impact investing and how Indian HNIs and UHNIs can approach it.

Article •14 November 2026
Top-down view of a winding spiral staircase

HNI

UHNI

Wealth Management

What Is Open-Architecture Wealth Management?

Learn how open-architecture wealth management works, how it differs from traditional wealth management, and what investors should know.

Article •12 November 2026
Ornate wooden desk and leather chairs in a traditional private office.

Entrepreneurs

UHNI

Family Office

Wealth Management

Why Family Offices Are Growing in India

Explore how rising wealth and increasingly complex investment needs is giving rise to a holistic way to manage wealth.

Article •10 November 2026
Soumya Rajan on a Mint Money thumbnail with the headline “How Rich People Invest Their Money

Global Investment

HNI

UHNI

Wealth Management

Alternative Investments

How Do Rich People Invest? In Conversation with Soumya Rajan

Soumya Rajan on a Mint Money thumbnail with the headline “How Rich People Invest Their Money

Podcast •08 August 2026
Airplane flying through a circular opening in a modern architectural structure.

Global Investment

HNI

UHNI

Wealth Management

What Is GIFT City? How Families Can Use It for Global Investing

Explore how Indian families can invest globally through GIFT City, including LRS, Family Investment Fund, tax considerations, benefits and risks.

Article •17 November 2026
Business professional in a suit holding a smartphone.

HNI

UHNI

Wealth Management

Bank-Owned vs Independent Wealth Management Firms in India

Compare bank-owned and independent wealth management firms in India, including fees, regulation, conflicts of interest and how to choose an advisor.

Article •16 November 2026
Stack of gold coins with a rupee symbol surrounded by grass and flowers. Related Article: ESG and Impact Investing

HNI

UHNI

Family Office

Impact Investing

What Is Impact Investing? A Guide for India’s HNIs & UHNIs

Understanding impact investing and how Indian HNIs and UHNIs can approach it.

Article •14 November 2026
Top-down view of a winding spiral staircase

HNI

UHNI

Wealth Management

What Is Open-Architecture Wealth Management?

Learn how open-architecture wealth management works, how it differs from traditional wealth management, and what investors should know.

Article •12 November 2026
Ornate wooden desk and leather chairs in a traditional private office.

Entrepreneurs

UHNI

Family Office

Wealth Management

Why Family Offices Are Growing in India

Explore how rising wealth and increasingly complex investment needs is giving rise to a holistic way to manage wealth.

Article •10 November 2026
Soumya Rajan on a Mint Money thumbnail with the headline “How Rich People Invest Their Money

Global Investment

HNI

UHNI

Wealth Management

Alternative Investments

How Do Rich People Invest? In Conversation with Soumya Rajan

Soumya Rajan on a Mint Money thumbnail with the headline “How Rich People Invest Their Money

Podcast •08 August 2026

Subscribe to WInsights to receive our content straight to your inbox every month.

Contact Us

Your legacy awaits

Fields marked with an asterisk (*) are required.

*Kindly note that this form does not operate as a job portal, and the HR Team will not receive information regarding your candidature

General Contact

+91 22 6621 0700

+91 75338 83388

info@waterfieldadvisors.com

Career

careers@waterfieldadvisors.com

Media

marketing@waterfieldadvisors.com

Follow Us

  • LinkedIn
  • YouTube
  • X
  • Instagram

Offices

142, 14th Floor, Maker Chambers VI, Nariman Point, Mumbai – 400021

7, Avighna House, 82, Dr. Annie Besant Road, Worli Naka, Siddharth Nagar, Worli, Mumbai, Maharashtra 400018

SEBI Office: Plot No. C4-A, 'G' Block, Bandra-Kurla Complex, Bandra(East), Mumbai – 400051

Worldmark 6, 3rd Floor, Gateway District, Aerocity, New Delhi, 110037

14th & 18th Floor, Berger Delhi One, Sector 16B, Noida, Gautam Budh Nagar – 201301

SEBI Office: NBCC Complex, Office Tower-1, 8th Floor, Plate B, East Kidwai Nagar, New Delhi – 110023

Level 5, No. 501, Prestige Garnet, 36, Ulsoor Road, Bengaluru – 560042

SEBI Office: 2nd Floor, Jeevan Mangal Building, No.4, Residency Road, Bengaluru – 560025

Workafella No.10, Uthamar Gandhi Salai, Nungambakkam High Road, Nungambakam, Chennai – 600034

SEBI Office: 7th Floor, 756-L, Anna Salai, Chennai – 600002

1-111, Raheja Woods 8, Central Avenue, Kalyani Nagar, Pune, MH 411006

SEBI Office: Plot No. C4-A, 'G' Block, Bandra-Kurla Complex, Bandra(East), Mumbai – 400051

916, PS Arcadia, Level 9, 4A, Camac Street, Kolkata 700016

SEBI Office: L&T Chambers, 3rd Floor, 16 Camac Street, Kolkata – 700017, West Bengal

GA-04, Block15, Ground Floor, Pragya Accelerator, Rd 1C, Gift City, Gandhinagar – 382355, Gujarat

1004, Regus Alacrity Business Center, Levana Cyber Heights, Vibhuti Khand, Gomti Nagar, Lucknow 226010

The Landmark Hotel, 10, The Mall, Kanpur – 208001

Insight with integrity

About

  • Overview
  • Leadership
  • Brand Story
  • Pressclub
  • Sustainability

Wealth Management

  • Family Business
  • Professionals and CXOs
  • Founders & Entrepreneurs
  • Women Clients

Asset Management

  • Discretionary PMS
  • Waterfield Fund of Funds
  • Smart Beta
  • Global Investment Managers
  • Winghts
  • Careers
  • Contact

waterfield financial and investment advisors private limited

SEBI Registration No
INA000001811
CIN No
U74900MH2012PTC234921
PMS REGISTRATION NO
INP000007818

Waterfield Foundation

CIN NO
U85300MH2023NPL397067

Waterfield Sponsor LLP

LLPIN
ABZ-9314

WATERFIELD INTERNATIONAL IFSC PRIVATE LIMITED

CIN No
U66190GJ2023PTC146493
IFSCA Reg No
IFSCA/FME/II/2025-26/174

Complaint Redressal Officer

Ms. Sweeti Suthar

[email protected]

Complaint Redressal Appellate Officer

Biplab Bhattacharya

[email protected]

Contact No:
+91 22 6621 0700

Waterfield Fund Managers Private Limited

CIN No
U65990MH2020PTC340389
FOF I
IN/AIF2/21-22/0876 (Category 2 AIF)
Name of the Fund Manager
Waterfield Fund Managers Private Limited
FOF II
IN/AIF2/23-24/1275 (Category 2 AIF)
Name of the Fund Manager
Waterfield Fund Managers Private Limited
Co-PMS
INP000008288

waterfield advisors private limited

CIN No
U74120MH2011PTC220601

Status of complaints

Beginning of the month: Nil

Received this month: Nil

Resolved during the month: Nil

Pending at the end of the month: Nil

Reason for pendency: N.A.

Principal Officer

Mr. Subodh Kaistha
Non-Individual Investment Advisor

Mr. Arun Prakash
Non-Individual Investment Advisor (PMS)

principal.officer@waterfieldadvisors.com
+91 22 6621 0700

Compliance & Grievance Officer

Ms. Darshana Bhutak

compliance@waterfieldadvisors.com

Investor Grievance

investor.grievance@waterfieldadvisors.com

Contact No:
+91 22 6621 0700

© 2026 Waterfield Advisors Pvt. Ltd.

  • Privacy Policy |
  • Disclaimer |
  • Regulatory Information